By merchantservices October 6, 2026
An established merchant may be able to remove personal guarantee merchant account obligations, but clean processing does not automatically cancel a signed guaranty. A stronger personal guarantee release request combines stable processing history, controlled disputes and refunds, stronger business financials, and a specific risk-replacement proposal. Treat the guaranty as active until an authorized party confirms the change in writing.
A personal guaranty that made sense when a business was new may deserve another look after the company develops a meaningful operating and processing record. That does not create an automatic right to release, but it can create leverage to renegotiate merchant agreement terms that were based on an earlier risk profile.
For a merchant trying to remove personal guarantee merchant account exposure, the central question is not simply how old the MID is. Underwriting is more likely to focus on whether the business itself now has enough financial strength, transaction history, liquidity, and operational stability to support its obligations without the same level of personal recourse.
If the account is still at the application stage, first understand when a personal guarantee may be required for a merchant account. Here, the issue is what happens later, after the merchant agreement guarantor has already signed and the business wants the original underwriting condition reconsidered.
Can You Remove a Personal Guarantee From a Merchant Account?
Yes. A processor or acquiring bank may agree to release, limit, or replace an existing personal guaranty.
There is generally no universal card-network rule or federal rule requiring a provider to release the guarantor after six months, one year, two years, or any other fixed period. A personal guarantee release remains primarily a contract and underwriting decision.
That means an attempt to remove personal guarantee merchant account liability can produce several different outcomes.
| Negotiated outcome | What it means |
| Full release | The individual is released according to the written amendment |
| Limited or capped guarantee | Personal exposure remains but is narrowed |
| Time-limited guarantee | The obligation ends according to defined conditions |
| Corporate guarantee substitution | A stronger business entity replaces or supplements the individual |
| Alternative collateral | A reserve, deposit, letter of credit, or other approved security replaces part of the personal support |
A release can also apply prospectively rather than retroactively.
For example, the written amendment could stop the guaranty from covering obligations created after a particular date while leaving previously incurred liabilities intact. That distinction is especially important with a continuing personal guarantee, because the scope and termination mechanics depend on the actual contract.
A salesperson’s statement that the PG “isn’t an issue anymore” is not the same as a contractual release.
What Does a Merchant-Account Personal Guarantee Actually Cover?
A processor personal guarantee gives the acquiring relationship another source of contractual recovery if the merchant cannot satisfy obligations covered by the agreement.
Depending on the contract, the guaranty may extend to:
- negative settlement balances;
- chargebacks;
- refunds and reversals;
- processing fees;
- assessments;
- indemnification obligations;
- collection expenses;
- other liabilities specifically defined in the merchant agreement.
The actual wording controls.
Qualpay’s current Merchant Card Processing Agreement, for example, contains a section titled “Continuing Guaranty.” It provides an example of how a continuing personal guarantee can be drafted and why the individual agreement should be read rather than assuming all providers use the same language.
This does not mean every merchant agreement uses Qualpay’s language. It simply illustrates how broad a guaranty can be when the contract expressly covers the merchant’s obligations.
Read Your Own Guaranty Before Negotiating
Before trying to remove personal guaranty from merchant agreement documents, search the signed application, program guide, merchant agreement, amendments, and addenda for:
- Personal Guaranty
- Personal Guarantee
- Continuing Guaranty
- Guarantor
- Obligations
- Survival
- Termination
- Reserve
- Security
- Collateral
- Amendment
- Waiver
- Release
The merchant agreement guarantor should pay particular attention to how obligations are defined, whether liability survives termination, and what process is required to modify the contract.
Those provisions tell you what you are actually asking underwriting to change.
Does closing the account cancel the guarantee?
Not necessarily.
Stopping new processing does not automatically eliminate chargebacks, refunds, reversals, fees, reserve claims, or other liabilities that originated while the account was active.
A business trying to remove personal guarantee merchant account exposure should therefore distinguish between closing the MID and obtaining an actual contractual release.
Why Processors Ask for Personal Guarantees
Merchant acquiring can involve financial exposure that remains after settlement.
A merchant may receive card proceeds today even though refunds, disputes, reversals, or product-delivery obligations remain unresolved. Businesses that take substantial payment before fulfillment can create an even longer exposure period.
A newly established company may also have limited assets or very little merchant account underwriting history. In that situation, an individual guarantor gives the acquiring relationship another potential source of repayment.
This is why a request to renegotiate merchant agreement terms becomes more persuasive when the company can show that its original risk profile has materially changed.
Instead of saying:
“We’ve been processing for two years, so the PG should be removed.”
A stronger statement is:
“The business now has a longer operating history, stronger liquidity, stable processing, controlled disputes, and materially stronger financial statements than it had when the account was originally approved.”
That gives the underwriter evidence to review.
The Processing History That Strengthens Your Case
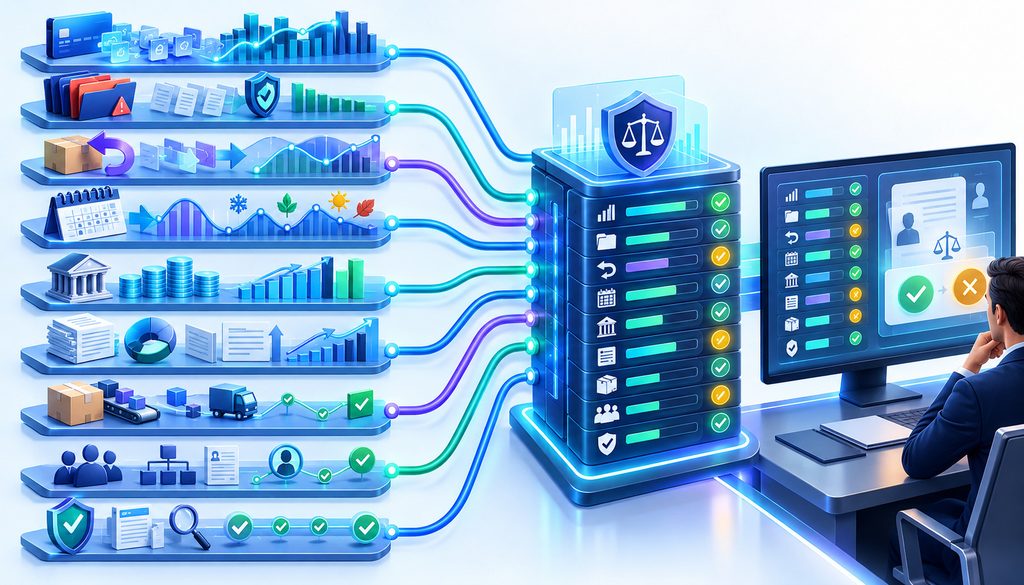
A clean processing history negotiation should be built around evidence, not an arbitrary anniversary date.
The provider may consider multiple parts of the account together.
| Underwriting factor | What strengthens the case | What may weaken it |
| Time on book | Meaningful stable history | Recently opened MID |
| Processing volume | Predictable, explainable activity | Sudden unexplained spikes |
| Chargebacks | Controlled dispute performance | Elevated or volatile disputes |
| Refunds | Stable and explainable | Large unexpected refund waves |
| Financial condition | Improving liquidity and net worth | Weak cash position |
| Bank activity | Stable operating balances | Repeated overdrafts |
| Seasonality | Documented recurring patterns | Unexplained peaks |
| Fulfillment | Predictable delivery cycle | Long future-delivery exposure |
| Account conduct | Few unresolved risk issues | Repeated risk reviews |
| Ownership | Stable ownership and control | Recent unexplained changes |
These are negotiation factors, not guaranteed approval thresholds.
Does 12 months of clean processing qualify you automatically?
No.
A longer merchant account underwriting history gives the risk team more actual performance data, but there is no universal “12-month rule.”
One full operating cycle can still help because the processor may have seen the business through ordinary sales peaks, refunds, disputes, and seasonal changes.
That additional history can make a clean processing history negotiation more credible without converting it into a contractual entitlement.
Chargebacks and Refunds Matter to the Release Request
A merchant can have years of account history and still present residual exposure if dispute or refund activity is unstable.
That is why the merchant account personal guarantee release request should include more than account age.
If dispute performance has been an issue, understanding how chargebacks arise and how preventable disputes can be reduced can help identify operational problems before another underwriting review.
Do not claim that a specific chargeback ratio guarantees approval.
Instead, show whether the business’s dispute activity is stable, explainable, and improving where improvement was needed.
For a business hoping to remove personal guarantee merchant account requirements, that factual record is more useful than simply stating that the company has been a customer for a long time.
Build the Evidence Package Before You Ask
A merchant account personal guarantee release request should look more like a focused credit file than a casual service ticket.
Start by asking the risk or credit team what it requires for a new merchant underwriting review.
Depending on the provider and business model, the package may include:
- recent merchant-processing statements;
- 12–24 months of processing history, if available;
- monthly sales history;
- transaction-volume trends;
- chargeback history;
- refund history;
- current balance sheet;
- profit-and-loss statement;
- business bank statements;
- retained earnings or liquidity data;
- current ownership information;
- fulfillment information;
- tax returns if requested;
- an explanation of rapid growth or seasonality.
Do not send sensitive tax or banking documents indiscriminately. Confirm what underwriting needs and use the processor’s approved secure method.
Show What Changed Since Original Underwriting
A strong merchant underwriting review should make the before-and-after story easy to understand.
| Original underwriting | Current business |
| Limited operating history | Several established operating cycles |
| Thin retained earnings | Stronger retained earnings |
| Mostly projected activity | Documented processing performance |
| Limited fulfillment history | Established fulfillment record |
| Modest liquidity | Stronger operating liquidity |
| Little processing data | Substantial processing history |
This comparison can help underwriting understand why the original credit condition may deserve reconsideration.
How to Ask the Processor to Remove the Personal Guarantee
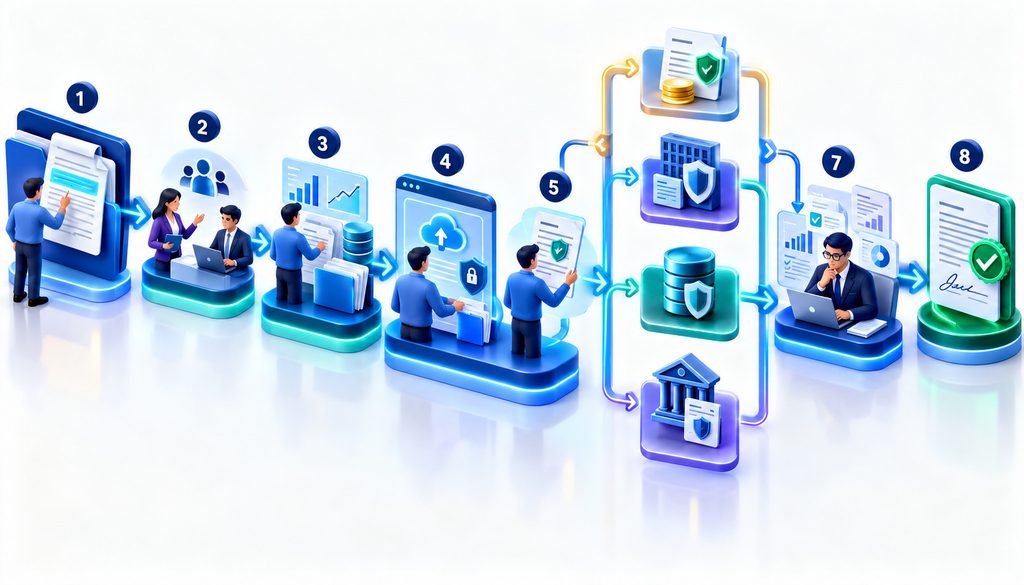
A merchant trying to remove personal guarantee merchant account liability should make a structured request.
Step 1: Locate the Exact Guaranty
Identify:
- who signed it;
- which legal entity is covered;
- what obligations are guaranteed;
- whether it is continuing;
- whether obligations survive termination;
- how the agreement can be amended;
- what reserve or collateral provisions already apply.
If your objective is to remove personal guaranty from merchant agreement obligations, you first need to know exactly which contractual language created them.
Step 2: Identify Who Has Approval Authority
The salesperson may be able to forward the request but may not be authorized to approve it.
Ask:
“Who has authority to approve a modification or release of the personal guaranty on this merchant account?”
The decision could involve underwriting, credit, risk, portfolio management, relationship management, or the acquiring bank.
Step 3: Present the Business Case
Summarize:
- account age;
- current monthly volume;
- transaction stability;
- chargeback performance;
- refund trends;
- liquidity;
- financial improvement;
- fulfillment exposure;
- changes since initial underwriting.
Avoid subjective descriptions such as “excellent account.”
Give the decision-maker information that can be documented in the credit file.
Step 4: Make an Exact Request
Start with the preferred result:
- full personal guarantee release;
- capped guarantee;
- time-limited guarantee;
- corporate guarantee substitution;
- reserve or another collateral structure.
This approach is more useful than asking only whether underwriting can “remove the PG.”
Step 5: Ask What Would Make Reconsideration Possible
If the request is declined, ask:
“What underwriting condition would need to change before this request could be reconsidered?”
The response might involve stronger financial statements, more processing history, lower exposure, collateral, or another review period.
The processor is not obligated to offer any particular alternative.
Step 6: Get the Change in Writing
This is critical.
The purpose of trying to remove personal guarantee merchant account exposure is not achieved by an informal reassurance.
Obtain an executed amendment, release, revised agreement, or another written document from the party with authority to change the contract.
What Else Can You Negotiate?
A guaranty does not have to remain an all-or-nothing term.
A business that cannot obtain full release may still be able to renegotiate merchant agreement exposure.
| Negotiation point | Potential result |
| Dollar cap | Limits total personal exposure |
| Expiration date | Ends the guaranty under defined terms |
| Covered obligations | Narrows the liabilities included |
| Prospective release | Stops coverage for future obligations |
| Corporate guaranty | Moves support to a stronger company |
| Reserve | Replaces some personal support with cash collateral |
| Letter of credit | Provides bank-backed security where accepted |
Where personal exposure is material, legal review of the amendment can be sensible.
Can a Corporate Guarantee Replace a Personal Guarantee?
Potentially.
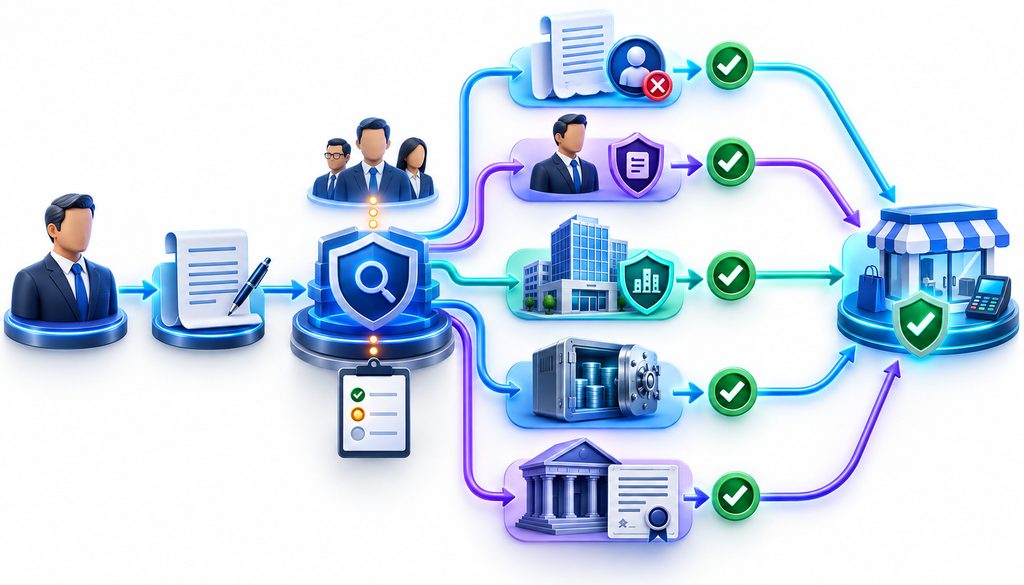
Corporate guarantee substitution becomes more realistic when a parent company or operating entity now has a financial position that gives the acquiring bank meaningful corporate recourse.
The underwriter must approve the change.
Do not assume that adding a corporate guaranty automatically removes the individual. A corporate guaranty merchant processing arrangement can sometimes supplement rather than replace a personal guaranty.
The written amendment should therefore state clearly whether the individual has been released.
For a financially strong company, a properly approved corporate guaranty merchant processing structure may be a useful middle ground when the provider will not approve a completely unsecured relationship.
Can a Reserve Replace the Personal Guarantee?
Sometimes, depending on underwriting policy.
Payarc/Evolve’s current terms provide one public example of a provider listing reserve accounts, transaction-level or account-level holds, rolling reserves, personal guarantees, corporate guarantees, and other financial instruments among possible exposure-mitigation measures.
That does not mean every acquirer will exchange a guaranty for a reserve.
A rolling reserve alternative also changes the economics of the account because some business cash is held back.
Before proposing that trade, understand how merchant-account reserves affect liquidity and how reserve terms can differ.
A rolling reserve alternative may reduce one form of exposure while creating another problem if too much working capital becomes restricted.
For that reason, trying to remove personal guarantee merchant account exposure should not become an excuse to accept an uneconomic collateral requirement without comparing the full agreement.
Can a Letter of Credit Be Used Instead?
A bank-issued letter of credit may be another possible form of security if the acquiring institution accepts it.
A letter of credit merchant account arrangement should not be presented as standard or universally available.
The merchant should consider:
- bank eligibility;
- collateral requirements;
- fees;
- expiration;
- renewal;
- drawing conditions;
- the processor’s required format;
- whether the individual guarantor is actually released.
A letter of credit merchant account proposal is most useful when the merchant already has a strong banking relationship and the acquiring institution confirms that this form of security is acceptable.
Sample Personal Guarantee Release Request
Subject: Request for Underwriting Review of Personal Guaranty
We are requesting an underwriting review of the personal guaranty associated with [Merchant Legal Name / MID reference].
The account was approved on October 6, 2026. Since that time, the company has developed a substantially longer processing history, stable transaction volume, controlled dispute and refund activity, and a materially stronger financial position than at initial underwriting.
We can provide current processing statements, financial statements, business bank information, and other documentation requested through the approved secure submission method.
We are requesting a full personal guarantee release.
If full release is not available, please advise whether underwriting would consider a capped or time-limited guaranty, corporate guaranty, reserve arrangement, letter of credit, or another form of substitute security.
Please also confirm which credit or underwriting team has authority to approve the requested change and what documentation is required.
Thank you for reviewing the account based on its current financial and processing profile.
Worked Example: How a Mature Merchant Builds the Case
Consider a hypothetical B2B ecommerce company.
When the account was opened, the company was young, had relatively modest retained earnings, and had limited processing data. The owner signed a processor personal guarantee as part of the approval.
Several years later, the company has:
- stable monthly volume;
- predictable seasonal patterns;
- controlled disputes;
- stable refunds;
- stronger retained earnings;
- better business liquidity;
- no unresolved negative settlement balance;
- stronger financial statements.
The company now wants to remove personal guarantee merchant account exposure based on the business’s current strength rather than the conditions that existed several years earlier.
Outcome A — Full Release Approved
Underwriting concludes that the business can support the account without individual recourse and approves the personal guarantee release.
The merchant retains the signed amendment, effective date, account identification, and language describing any obligations that remain covered.
Outcome B — Capped Guaranty Offered
The acquirer will not agree to full release but offers to limit the guaranty.
That does not eliminate personal exposure, but it can materially change the owner’s risk.
Outcome C — No Modification
The provider’s policy requires the existing structure to remain.
At that point, the merchant can decide whether to stay or test whether another acquiring institution will approve a merchant account without personal guarantee requirements.
None of these outcomes should be described as typical without provider-specific evidence.
Why Might the Processor Refuse?
A refusal does not necessarily mean the account has performed poorly.
Possible reasons include:
- acquiring-bank policy;
- future-delivery exposure;
- substantial prepayments;
- weak business balance sheet;
- high average ticket;
- high maximum ticket;
- seasonal exposure;
- dispute volatility;
- concentration risk;
- ownership changes;
- existing credit policy.
Some businesses also receive tighter controls because their model creates more residual exposure for the acquiring institution. Understanding why certain merchant accounts receive stricter underwriting, reserves, or monitoring can help distinguish weak performance from a broader underwriting-policy decision.
This distinction matters to any merchant attempting to remove personal guarantee merchant account obligations.
If underwriting says more history is needed, another review later may make sense.
If the acquiring bank has a fixed policy requiring an individual guarantor for that business model, simply waiting another year may accomplish nothing.
Does Changing From an LLC to a Corporation Remove the Guaranty?
No automatic release should be assumed.
An entity conversion, creation of a new corporation, ownership transfer, assignment, and migration of processing to a different legal entity are separate events.
The result can depend on:
- the merchant agreement;
- guaranty language;
- successor provisions;
- assignment restrictions;
- the structure of the transaction;
- whether a new application is required;
- whether a novation occurs;
- whether an actual written release is executed;
- applicable state law.
A merchant agreement guarantor should not assume that forming a new corporation erases an individually signed obligation.
The same concern applies to a continuing personal guarantee. If the existing language remains effective, restructuring the business does not necessarily terminate it.
Get written instructions from the processor or acquirer before moving transactions to another entity.
Renewal and Repricing Can Improve Negotiating Leverage
A merchant account renewal negotiation can provide a natural opportunity to revisit an old guaranty requirement.
Other useful moments may include:
- repricing;
- sustained processing growth;
- completion of several operating cycles;
- significant improvement in financial statements;
- acquisition by a stronger parent;
- competitive underwriting.
A professional way to approach the discussion is:
“Another acquiring relationship has indicated that our current financial profile may qualify without an individual guaranty. Before making a change, we’d prefer to determine whether our existing underwriting conditions can be updated.”
Do not fabricate another offer.
A real competing approval gives the current provider a legitimate reason to reconsider the account.
The objective of a merchant account renewal negotiation should be broader than simply demanding the removal of one clause. It is an opportunity to evaluate whether the entire underwriting structure still fits the business.
Compare the Whole Agreement, Not Just the Personal Guarantee
A merchant account without personal guarantee language is not automatically a better contract.
Consider two hypothetical offers:
| Contract term | Existing account | Competing account |
| Personal guaranty | Unlimited | None |
| Reserve | None | Significant reserve |
| Pricing | Lower | Higher |
| Funding | Faster | Slower |
| Processing limits | Appropriate | More restrictive |
| Termination | Flexible | Longer commitment |
| Equipment | Owned | Lease obligation |
A business may successfully remove personal guarantee merchant account liability and still end up with a less attractive arrangement if the replacement account imposes heavy reserves, restrictive processing limits, slower funding, or unfavorable termination terms.
Compare:
- pricing;
- reserve requirements;
- reserve release provisions;
- funding;
- processing limits;
- average ticket;
- maximum ticket;
- chargeback procedures;
- equipment obligations;
- amendment rights;
- termination terms;
- surviving liabilities.
The goal is not simply a merchant account without personal guarantee language. The goal is a merchant agreement whose overall economics and risk allocation make sense.
When Is Release More Realistic?
A release may become more realistic when the business has:
- substantial operating history;
- meaningful retained earnings;
- stronger business liquidity;
- a healthy balance sheet;
- stable processing;
- predictable fulfillment;
- controlled disputes;
- stable refunds;
- limited residual exposure;
- a financially strong parent;
- acceptable alternative collateral.
By contrast, underwriting may remain cautious with:
- startups;
- thinly capitalized companies;
- future delivery;
- substantial prepayments;
- large transactions;
- volatile disputes;
- rapid unexplained growth;
- major ownership changes.
These are underwriting characteristics rather than universal legal classifications.
For a merchant trying to remove personal guarantee merchant account requirements, the best argument is usually that the business itself has become a materially stronger credit than it was at original approval.
Personal Guarantee Release Negotiation Checklist
Before Contacting the Processor
- Locate the signed guaranty.
- Locate the current merchant agreement.
- Confirm amendment requirements.
- Review survival language.
- Summarize processing history.
- Review dispute and refund trends.
- Prepare current financial statements.
- Document improved liquidity.
- Decide which collateral alternatives are acceptable.
- Define the preferred result.
During the Discussion
- Request a formal merchant underwriting review.
- State the exact modification requested.
- Ask about full release.
- Ask about a cap or expiration date.
- Ask about corporate guarantee substitution.
- Ask about a reserve or letter of credit.
- Ask what caused a denial.
- Ask when reconsideration might make sense.
- Keep material communications documented.
Before Treating the Matter as Closed
- Obtain the signed release or amendment.
- Verify the effective date.
- Identify any prior obligations that remain covered.
- Confirm new collateral requirements.
- Confirm reserve mechanics.
- Retain signed copies permanently.
Mistakes That Weaken the Request
- Assuming account age automatically creates a release right.
- Relying solely on a salesperson rather than the authorized underwriting party.
- Applying immediately after a dispute spike.
- Leaving material growth unexplained.
- Submitting incomplete financial statements.
- Asking only for full removal without considering alternatives.
- Relying on a verbal promise.
- Assuming an entity change cancels the old guaranty.
- Bluffing about another processor’s approval.
- Focusing on the PG while ignoring reserves and other contract provisions.
A well-prepared merchant account personal guarantee release request makes it easier for the credit team to understand why the original underwriting decision deserves another look.
When Should You Consider Another Merchant Account?
Shopping the account can make sense when the business has materially improved but the current provider will not reconsider an old guaranty requirement.
A genuine competitive approval can reveal whether another acquiring institution views the business differently.
Do not terminate the existing account before the replacement is fully approved.
Before moving, understand:
- approved monthly volume;
- average and maximum ticket limits;
- funding;
- reserves;
- outstanding chargebacks;
- final settlement;
- equipment obligations;
- recurring billing migration;
- token migration where applicable;
- termination terms;
- surviving obligations.
A new MID does not automatically eliminate obligations from the old account.
Industry Data Note
Reliable public statistics showing how often merchant-account personal guarantees are later released are limited because these decisions generally occur through private credit and contract negotiations.
For that reason, claims such as “processors normally release personal guarantees after 12 months” should not be presented as established industry facts without a documented provider policy.
Merchant agreements and guaranties vary by provider and applicable state law. This article provides general operational information and does not constitute individualized legal advice.
Frequently Asked Questions
Can I remove a personal guarantee from my merchant account after one year?
Possibly, but one year does not create an automatic release right. If your objective is to remove personal guarantee merchant account liability, one year of clean history can add useful evidence, but underwriting can still approve, decline, or offer a narrower modification.
How much processing history do I need for a personal guarantee release?
There is no universal minimum. Longer stable history generally gives underwriting more actual information about transaction volume, disputes, refunds, fulfillment, and account conduct.
Does closing a merchant account cancel the personal guarantee?
Not necessarily. Survival provisions and previously created obligations can remain relevant after processing stops. Closing the MID and obtaining a contractual release are separate issues.
Can an LLC protect me after I signed a personal guarantee?
An LLC does not automatically eliminate an individually signed contractual obligation. The guarantee, amendments, entity structure, applicable law, and any written release determine the result.
Can a corporate guarantee replace a personal guarantee?
Potentially. A financially strong company or parent may be acceptable to underwriting, but the provider must approve the substitution and document whether the individual has actually been released.
Can a rolling reserve replace a personal guarantee?
Some providers may consider a reserve or another collateral structure, but policies vary. A reserve can also restrict working capital, so the merchant should compare the liquidity cost with the reduction in personal exposure.
Should I propose a letter of credit?
It may be worth discussing if the acquiring institution accepts bank-issued security and the company has a strong banking relationship. Review fees, collateral requirements, expiration terms, and whether the arrangement actually results in release of the individual guarantor.
What if my processor refuses to remove the guarantee?
Ask what specifically caused the denial. If the issue can improve—such as financial strength or account history—you may be able to return with a stronger file. If it is a fixed policy, competitive underwriting may provide more useful information.
Does changing from an LLC to a corporation cancel the guarantee?
No automatic cancellation should be assumed. Entity conversion, assignment, new-company formation, and novation are separate legal and contractual events.
Do I need a lawyer to negotiate the release?
The initial underwriting request can often be made without counsel. Legal review becomes more useful when the guaranty is broad, uncapped, involves significant personal assets, or is being altered through a major contractual or entity restructuring.
The Goal Is a Written Release, Not a Verbal Promise
If you want to remove personal guarantee merchant account exposure, focus the negotiation on what has materially changed since the original approval.
Stable processing, controlled disputes and refunds, stronger liquidity, improved financial statements, documented fulfillment, and a longer processing history can all strengthen the case.
They do not create an automatic entitlement to release.
A merchant may instead receive a full release, capped guaranty, expiration date, corporate guaranty, reserve requirement, letter of credit, or no modification at all.
That is why the final objective in any effort to remove personal guarantee merchant account liability is an executed document—not a verbal assurance.
Until the authorized party provides a clear written release or amendment identifying the effective date and remaining obligations, assume the original guaranty continues according to its terms.
Leave a Reply